Chapter 2 - Untangling the Financial Lifeline
Driving away from my parents’ house that holiday evening, the heater in my Ford F-250 hummed softly, keeping the bitter Ohio chill at bay. My hands gripped the steering wheel, still trembling slightly from adrenaline and pure, unadulterated disbelief. For years, I had convinced myself that keeping the peace meant footing the bill. Whenever a crisis struck—whether it was medical bills, broken leases, or car troubles—my family dialed my number before anyone else's. I had built a successful commercial lighting business from the ground up through sixty-hour workweeks, and instead of earning their respect for my work ethic, it had simply turned me into their personal ATM.
By the time I reached my apartment in Columbus, my phone had already started buzzing. It was Mom, followed immediately by a text message from Ethan demanding to know why my company credit card had been declined at a local diner on our way home. I silenced the ringer, tossed the phone onto the kitchen counter, and sat down at my laptop to wait for Melissa’s preliminary report.
True to her professional form, Melissa’s email landed in my inbox just before midnight. The sheer scale of what I had been quietly subsidizing layout across the screen like a corporate audit. It wasn't just occasional help; it was an entire lifestyle.
For starters, my parents’ suburban home in Dayton was entirely maintained by my bank accounts. I had been paying their monthly electric bill, water, municipal gas, high-speed internet, and home insurance premiums for over thirty-six months. On top of that, there were recurring pharmacy drafts for my mother's blood pressure medication, quarterly property tax installments that Dad always seemed to "forget" until the county threatened liens, and a sprawling bundle of streaming and entertainment subscriptions.
Then came Ethan’s ledger. Beyond the rent deposits and phone bills he mentioned, Melissa’s audit revealed I was paying his car insurance policy on a sports car he couldn't afford, his gym membership, his health insurance deductible payments, and even a monthly retainer for a credit-repair service he needed after maxing out three separate credit cards on weekend trips to Chicago. In total, my automatic monthly expenditures supporting my family hovered just north of $4,505.
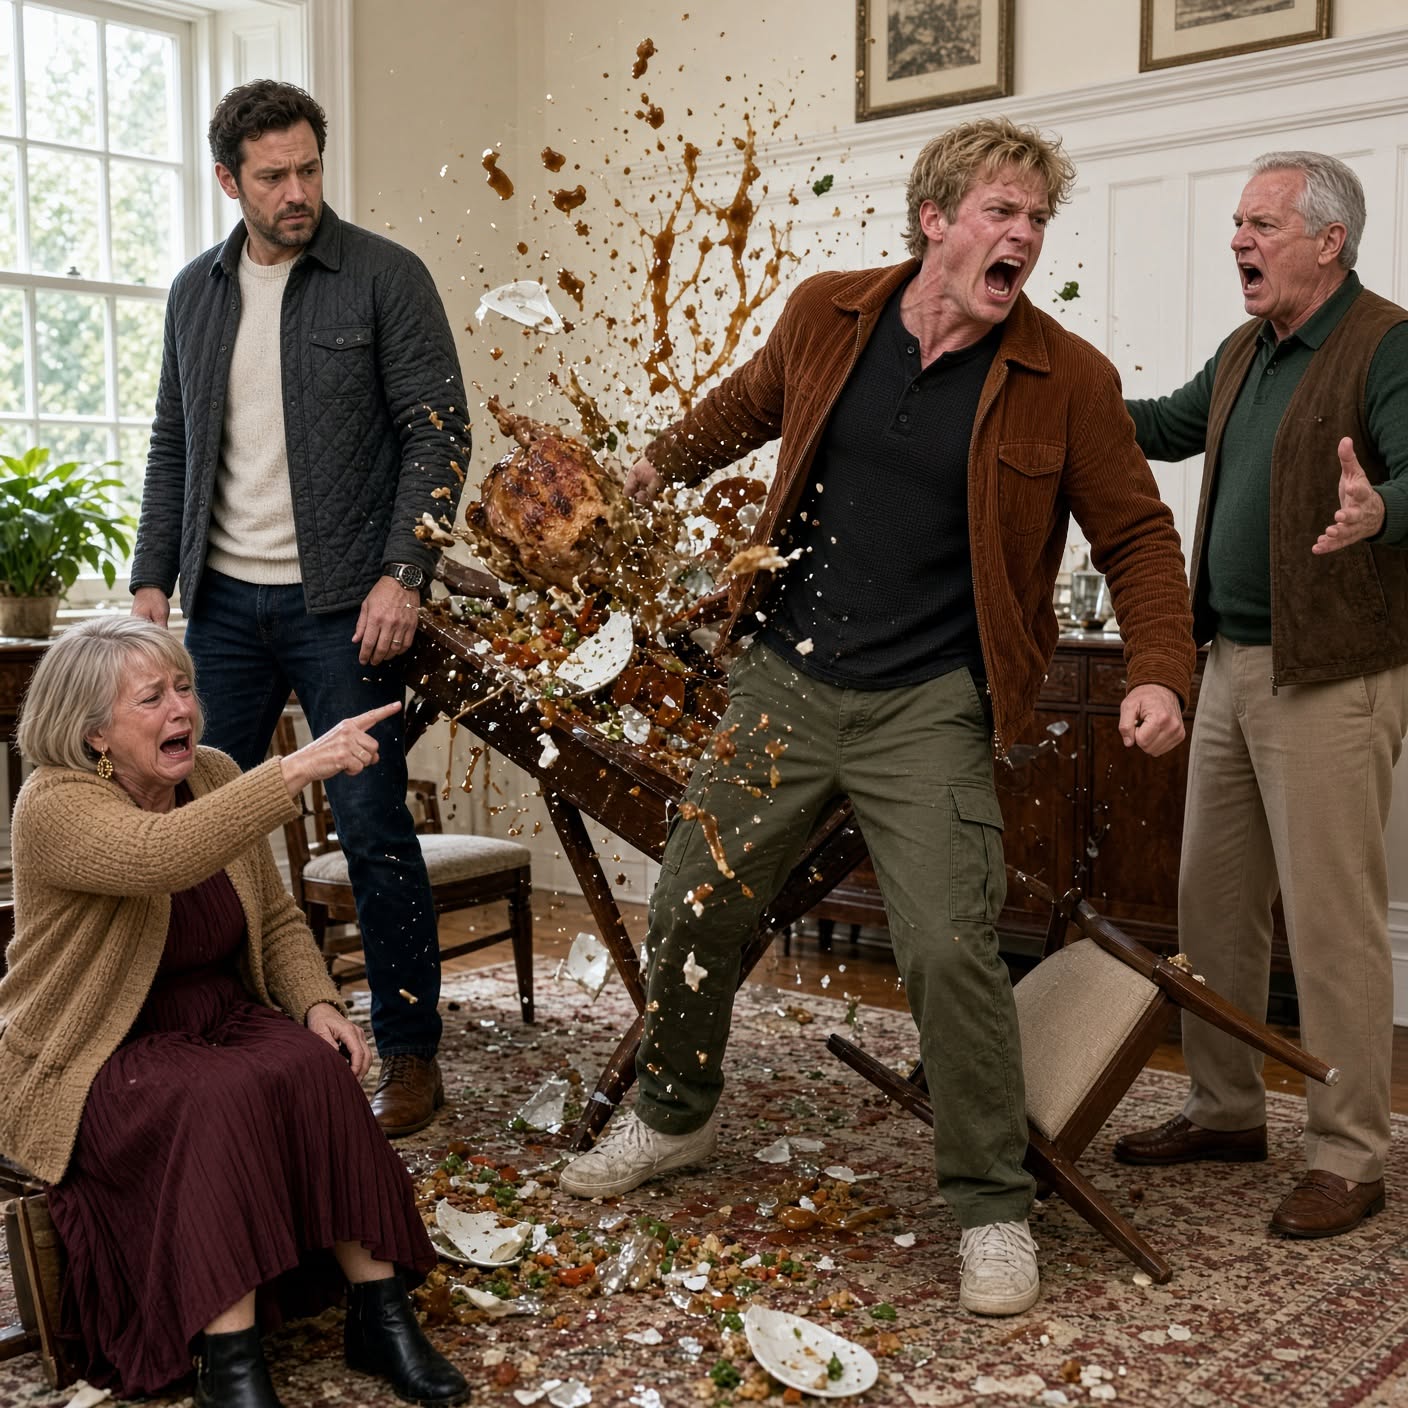
And how had they repaid me? By trashing a dining room, screaming obscenities, throwing a tantrum like an entitled toddler, and blaming me for a brotherly meltdown because I refused to hand over my livelihood for a month.
I highlighted the entire list of automatic clearing house (ACH) authorizations, merchant bill-pays, and recurring credit card charges. With a single click, I authorized Melissa to draft formal stop-payment notices to every utility provider, insurance underwriter, and subscription service tied to my parents' and brother's households.
"It's done," Melissa replied via text a few minutes later. "All scheduled drafts have been blocked at the bank level. They’re on their own, Daniel."
May you like
I leaned back in my office chair, looking out at the glittering city skyline. Let them figure out what life actually cost.
---